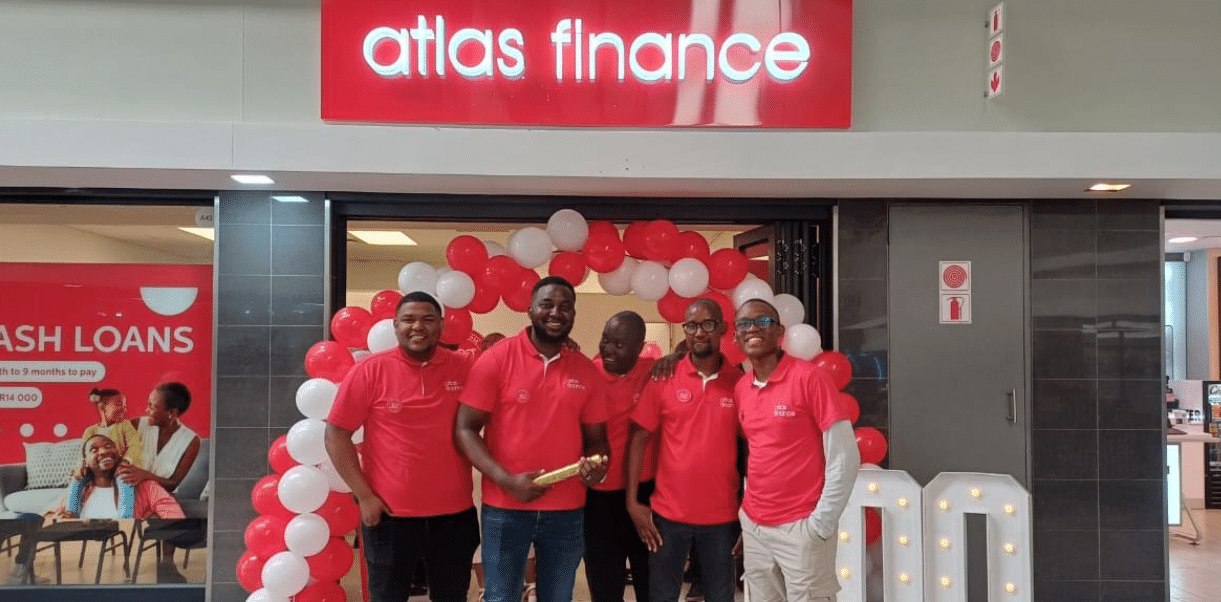
The milestone signals more than expansion for a business that has spent over three decades serving South Africans who may struggle to access traditional banking services. For Atlas Finance, physical branches remain an important part of helping customers understand their options, ask questions and navigate the credit process with confidence.
“This achievement reflects more than business growth, it speaks to the real need for accessible financial services in communities where people want support that is close to home, easy to access and built around their everyday realities,” says Niresh Gopichand, Risk Director at Atlas Finance.
“For millions of South Africans who remain underserved by traditional banking, a physical branch is far more than a building, it is often the first point of trust. The ability to sit across from someone, ask questions, understand the process and access credit with confidence and dignity remains deeply important.”
Three decades of serving underserved communities
Founded in 1994, Atlas Finance has assisted more than three million South Africans. Its latest milestone reflects a deliberate strategy to establish branches in communities where demand is high and access to financial services has historically been limited.
As economic conditions change and customer needs evolve, the company says it continues to adapt its offerings while maintaining a physical presence in the areas it serves.
The expansion comes at a time when digital innovation is reshaping how people interact with financial institutions. However, Atlas Finance believes that technology alone cannot address every barrier to access.
For customers facing limited internet connectivity, high data costs or low financial literacy, face-to-face support can remain an important part of making informed financial decisions.
“Branches are not a step backwards, they are enablers of inclusion and job creation in our communities,” adds Gopichand. “They create spaces where customers feel seen, heard and supported when making financial decisions that impact their lives.”
A loan solution designed for domestic workers and gardeners
One example of Atlas Finance’s approach to serving customers with different income circumstances is its specialised loan product for domestic workers and gardeners.
Launched three years ago, the product has recorded year-on-year growth of 49.2%. It enables eligible customers to access credit based on banked income rather than payslips, addressing a key barrier for people working in informal employment arrangements.
The uptake highlights a need for financial products that reflect how people earn their income, particularly those who may not have the conventional employment documentation often associated with formal credit applications.
By tailoring its offering to this customer group, Atlas Finance aims to provide an alternative to informal lending and help more people participate in the formal financial system.
The company describes the product as part of its broader effort to make financial services more accessible while responding to the realities of customers’ everyday lives.
Combining digital innovation with human connection
Digital services continue to change the financial sector, but Atlas Finance believes a hybrid model that combines technology with a physical branch network is important for building trust and extending access.
For customers who face digital barriers, being able to speak directly to someone can help clarify how a product works and what the process involves. This personal engagement can be particularly valuable when borrowing decisions affect household budgets and other essential expenses.
The company’s position is that physical branches and digital innovation can complement each other, rather than one necessarily replacing the other.
Its nationwide footprint is therefore central to its stated approach to financial inclusion, giving customers the opportunity to engage with the business in person while the financial services landscape continues to evolve.
Financial education and consumer protection matter
Access to credit is only one part of the financial inclusion challenge. Atlas Finance also invests in financial education and consumer protection, helping customers understand their rights and make informed choices.
This work is particularly relevant in an environment where illegal lenders, commonly known as mashonisas or loan sharks, can exploit vulnerable people.
Helping consumers understand financial products, their rights and the choices available to them can support better-informed decisions. For Atlas Finance, education and protection form part of its wider role in the communities it serves.
Looking beyond the 300-branch milestone
For Atlas Finance, reaching 300 branches is a significant business milestone, but the company says its attention remains on the needs of customers who still face barriers to accessing finance.
“As we celebrate this milestone, our focus remains firmly on the future,” says Gopichand. “Access to credit can change lives when it is provided responsibly and with empathy. For many people, it means being able to put food on the table, keep a small business going, pay school fees or get through an unexpected setback. There is still a long way to go in closing the gap in access to finance, and our role is to keep listening, evolving and showing up for the communities that rely on us most.”
As Atlas Finance expands its physical presence, its central message is that financial inclusion involves more than making credit available. It also means ensuring that people can access information, understand their options and engage with financial services in ways that reflect their circumstances.
With 300 branches nationwide and more than three million South Africans assisted since its founding, the company is positioning its next chapter around continued access, customer support and financial inclusion.